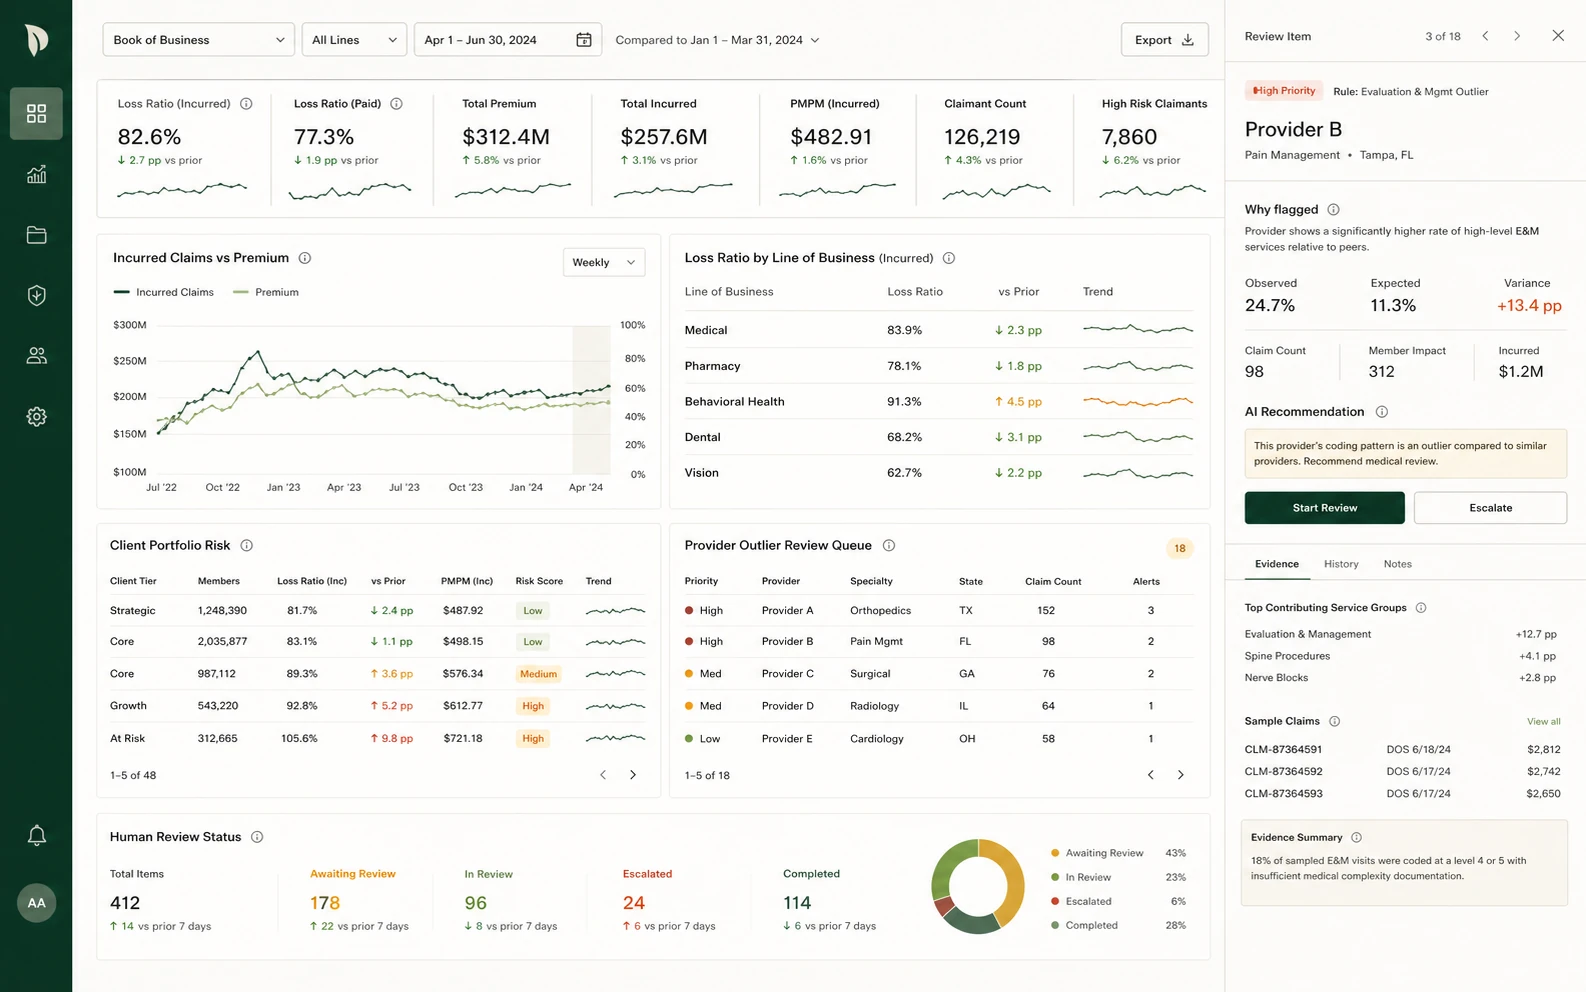
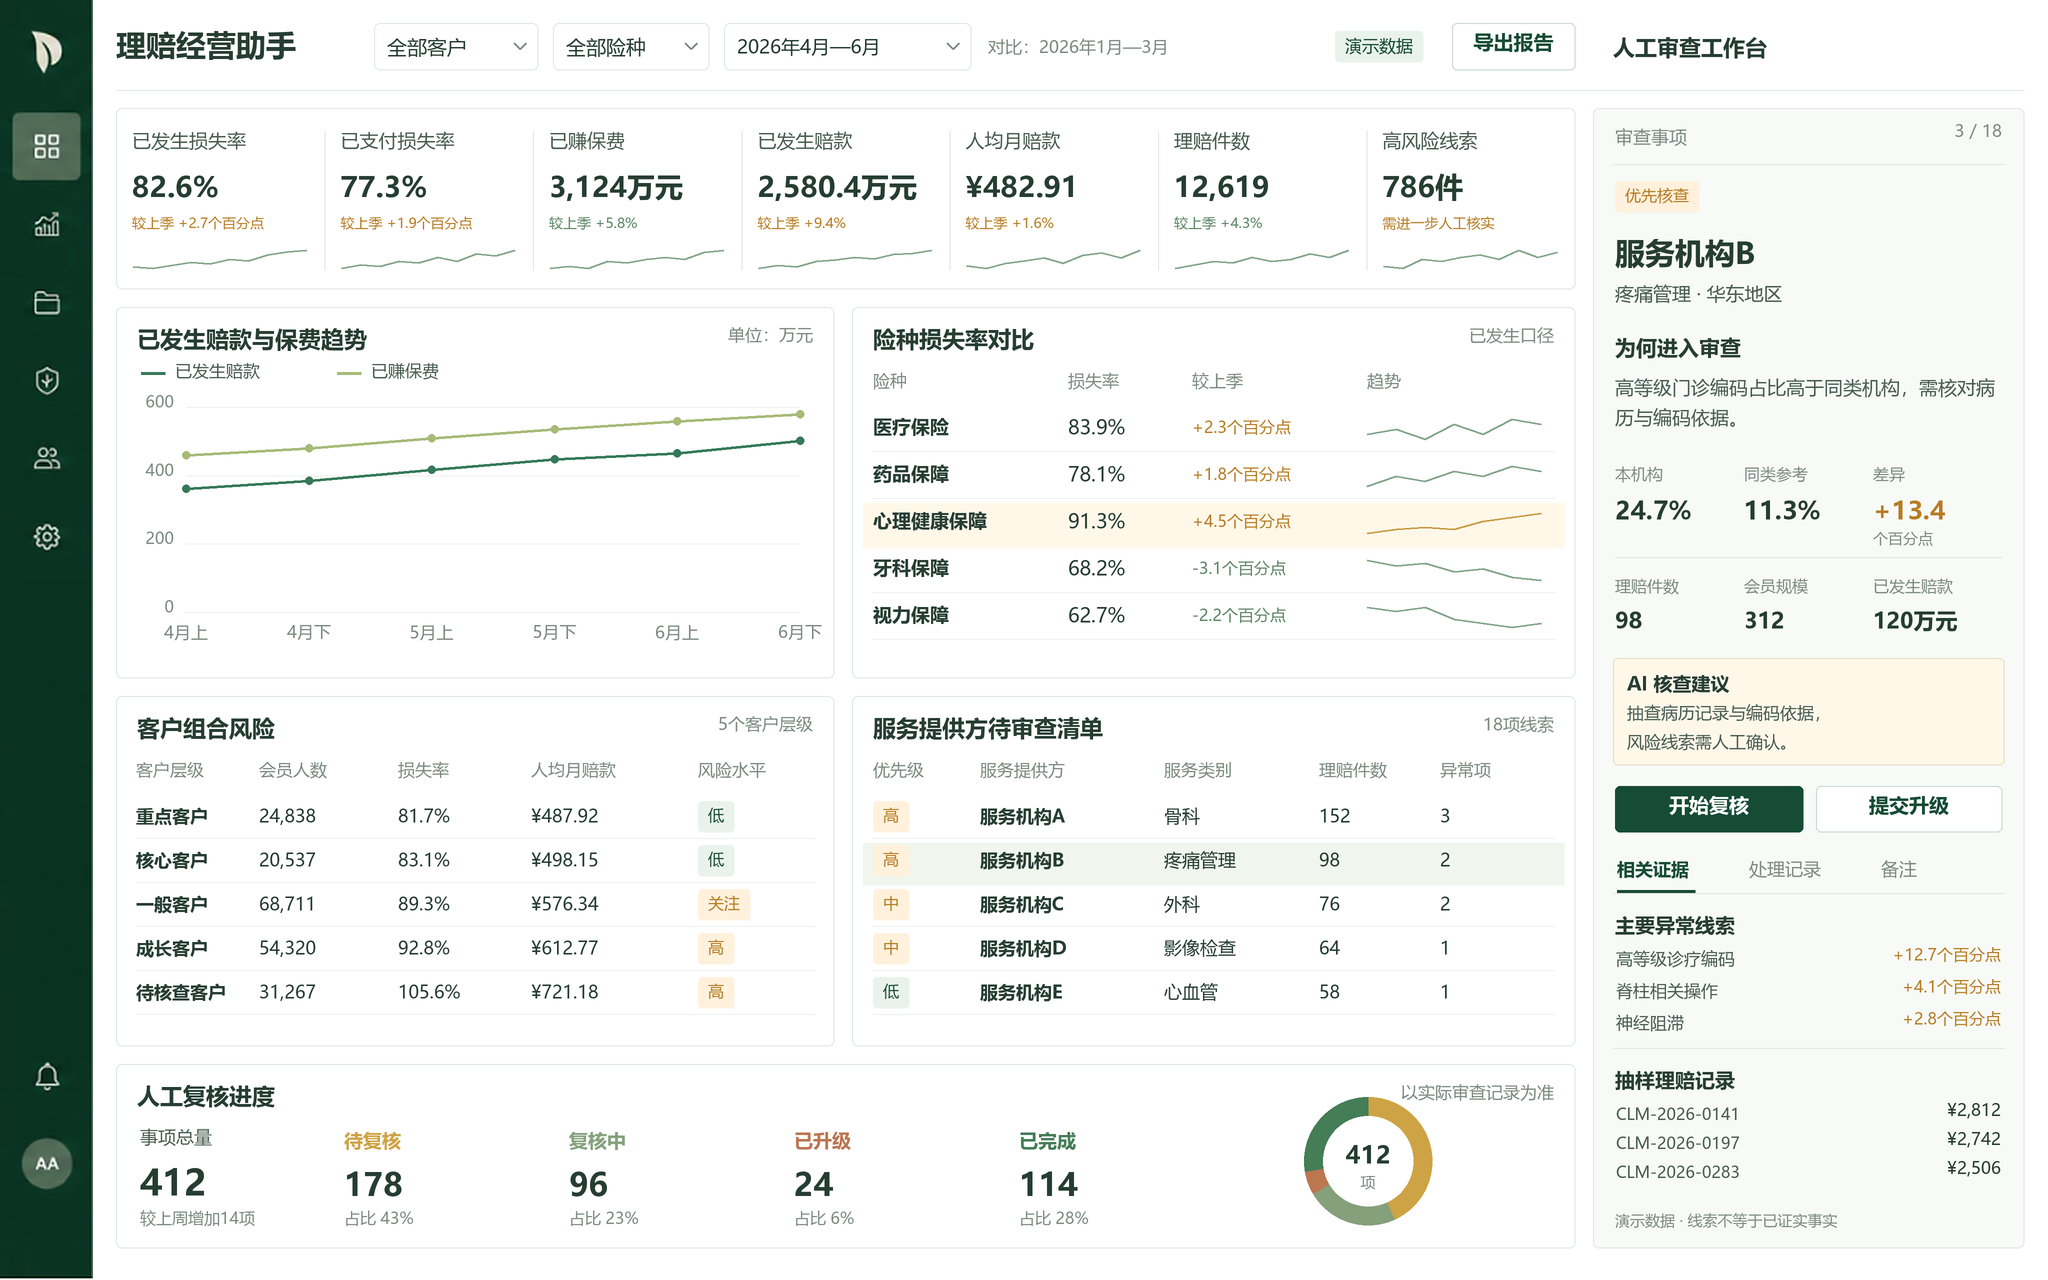
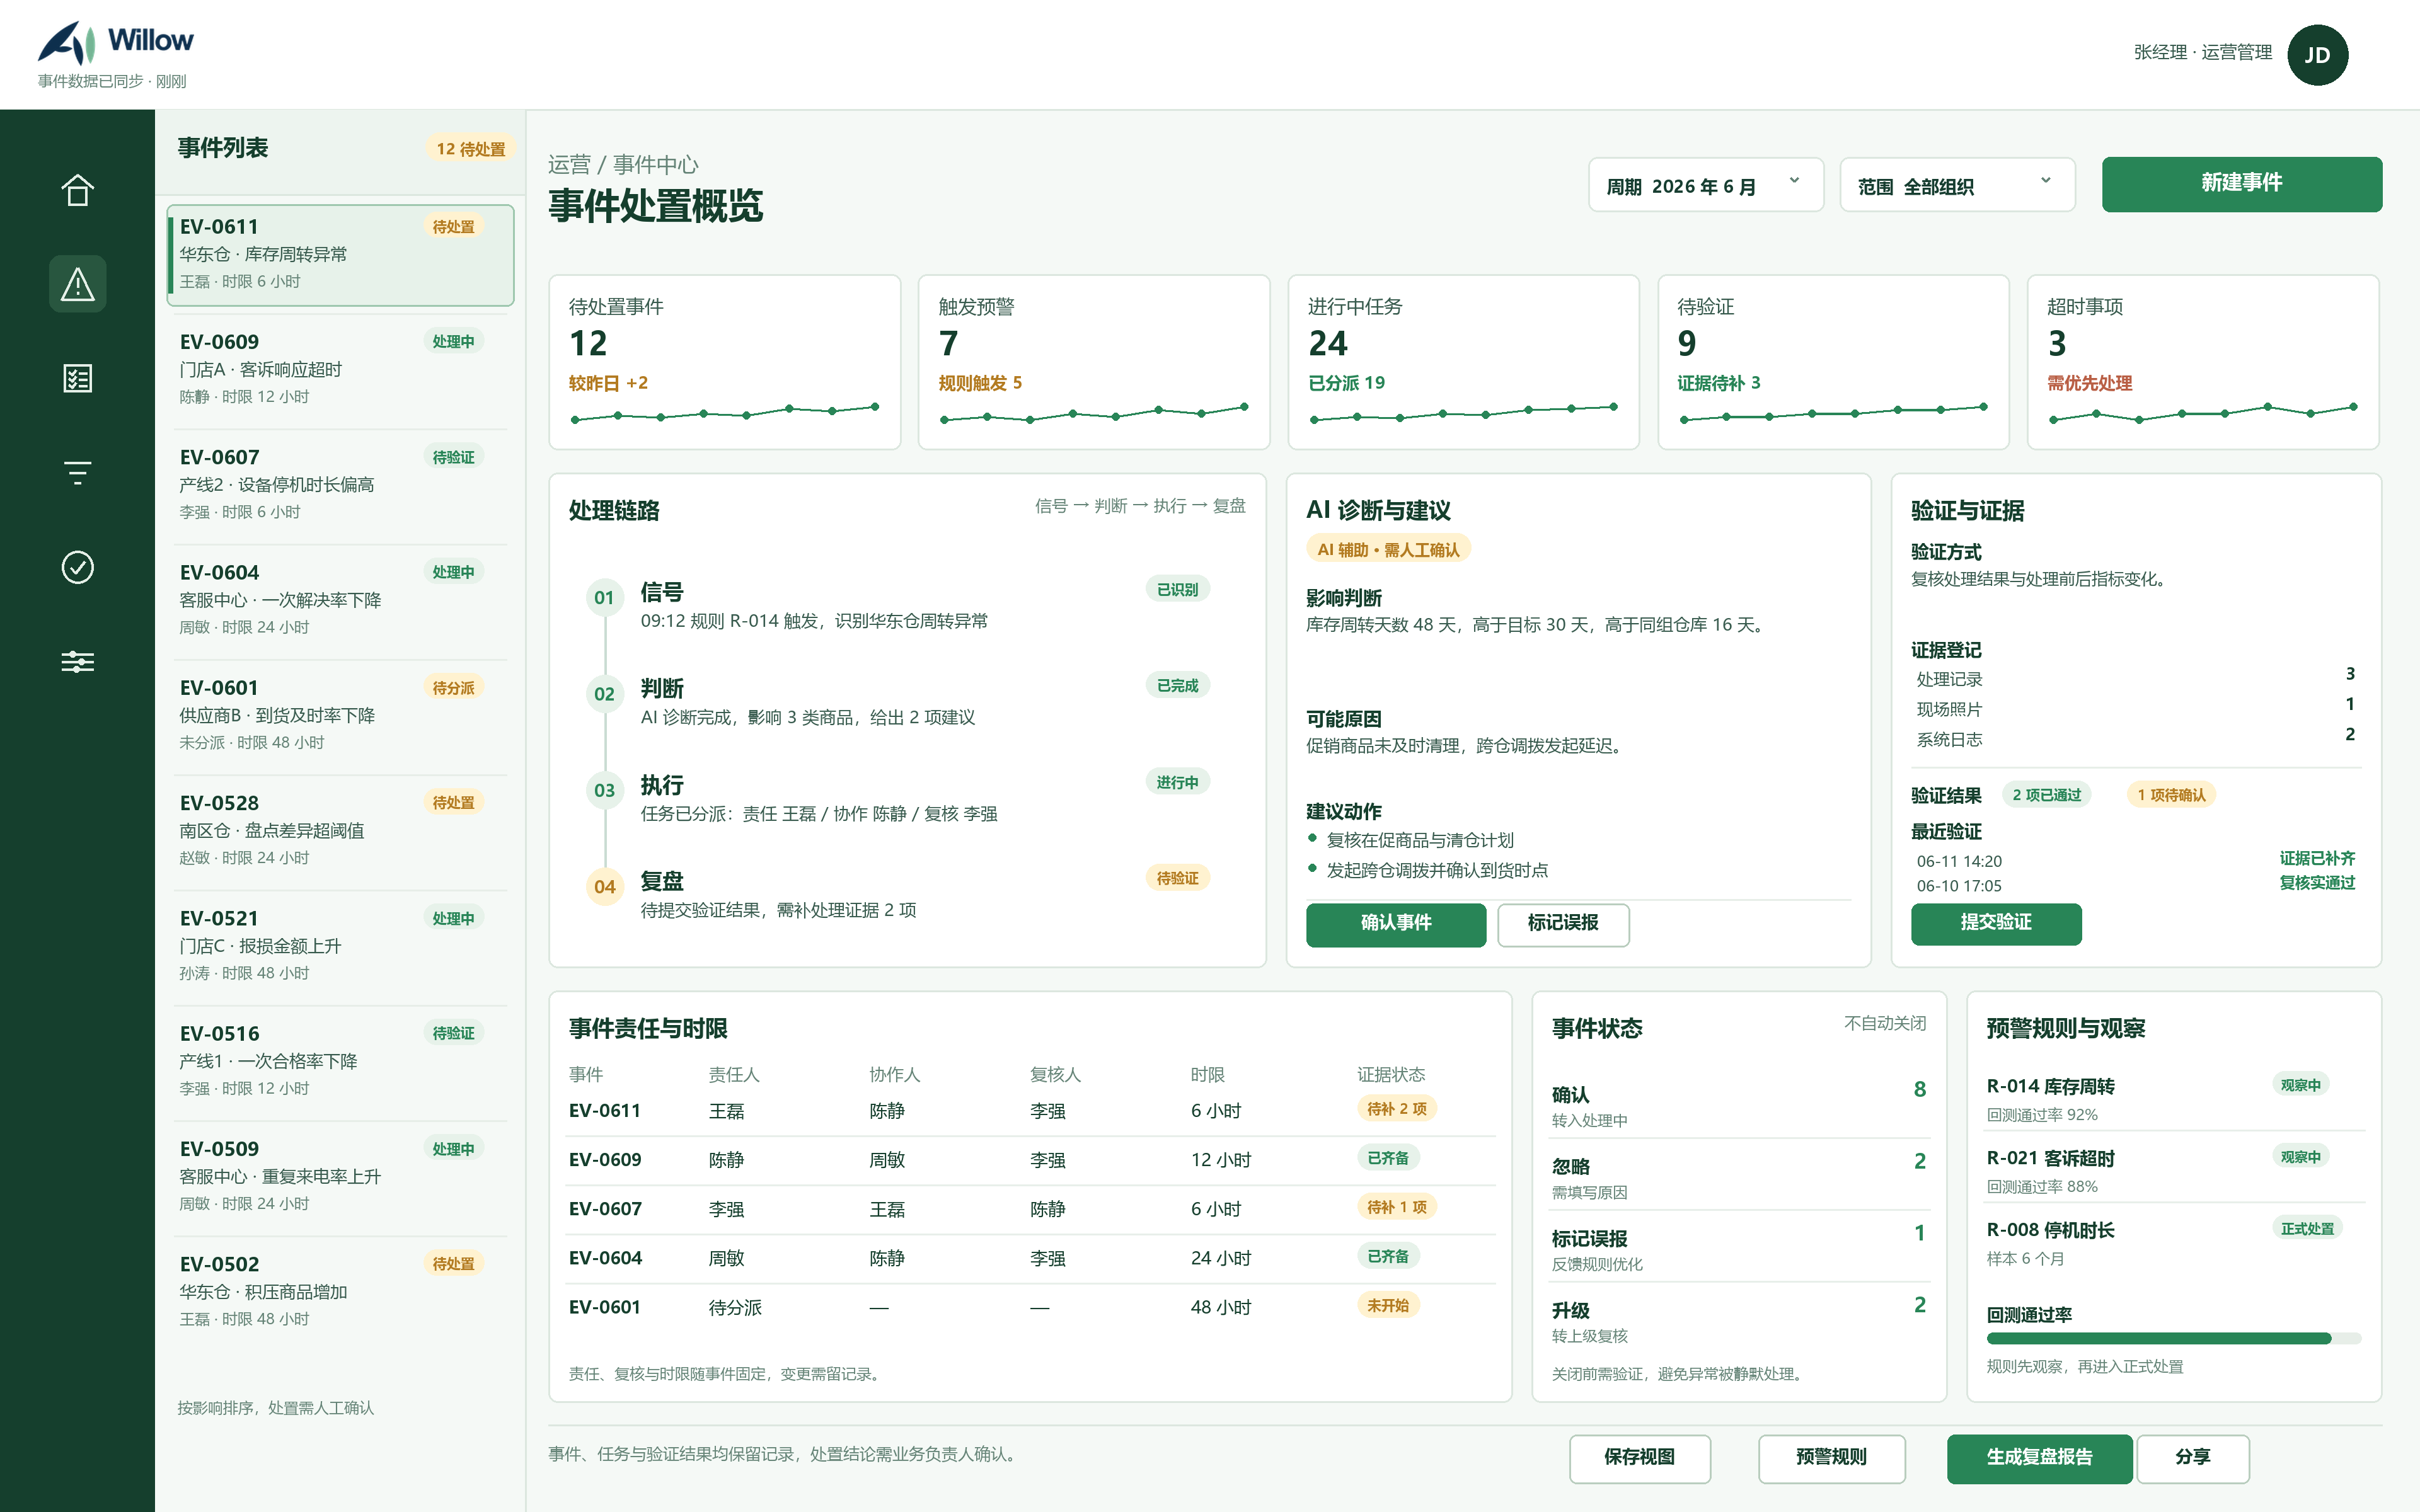
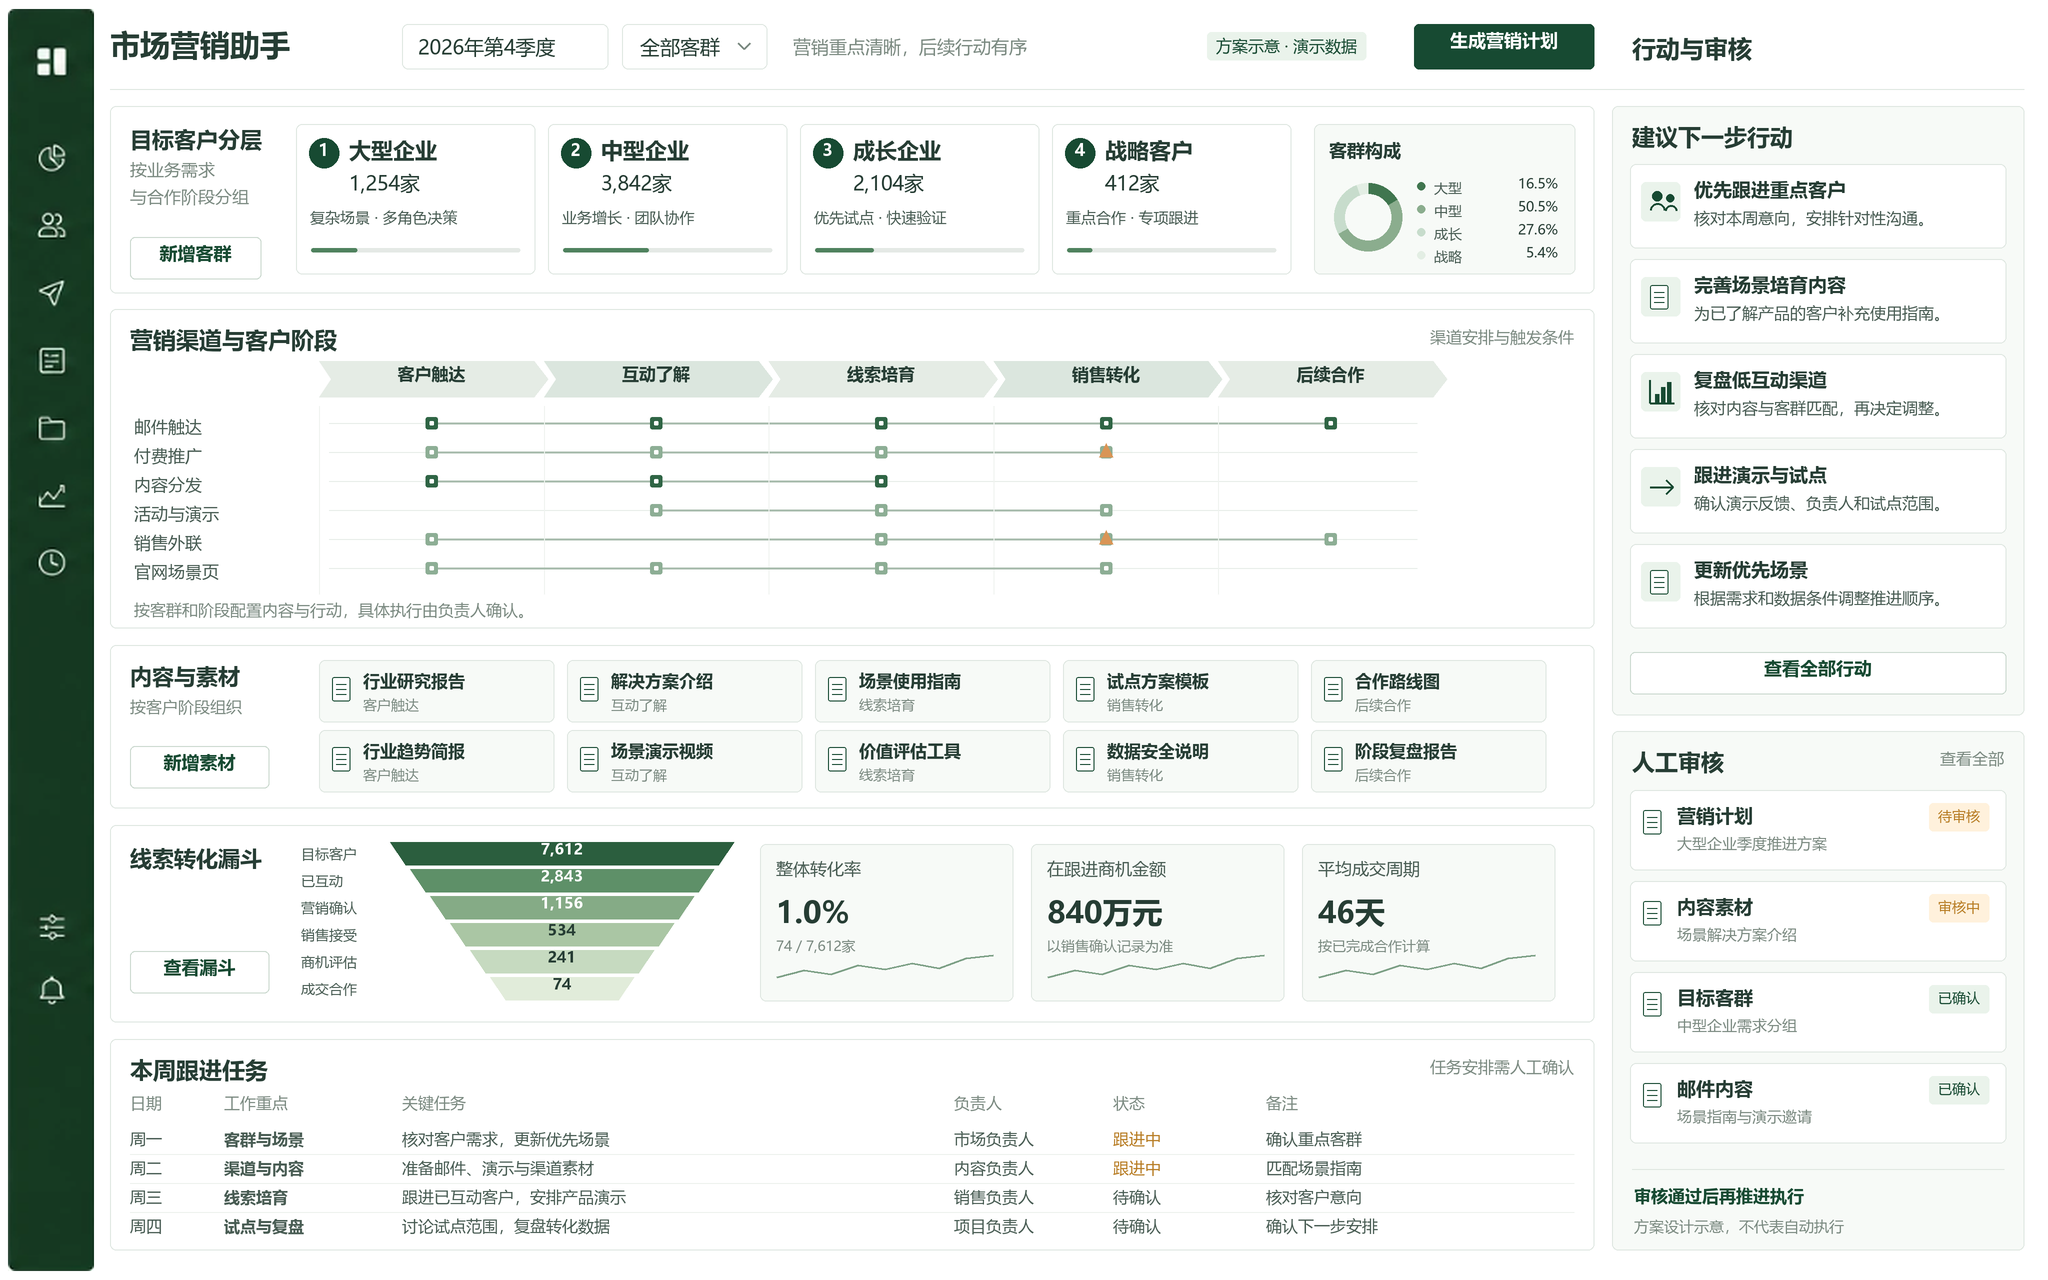
For group health and commercial insurance operations, it organizes loss ratios, risk leads, evidence and a human follow-up loop around policy, customer, claims and provider data.
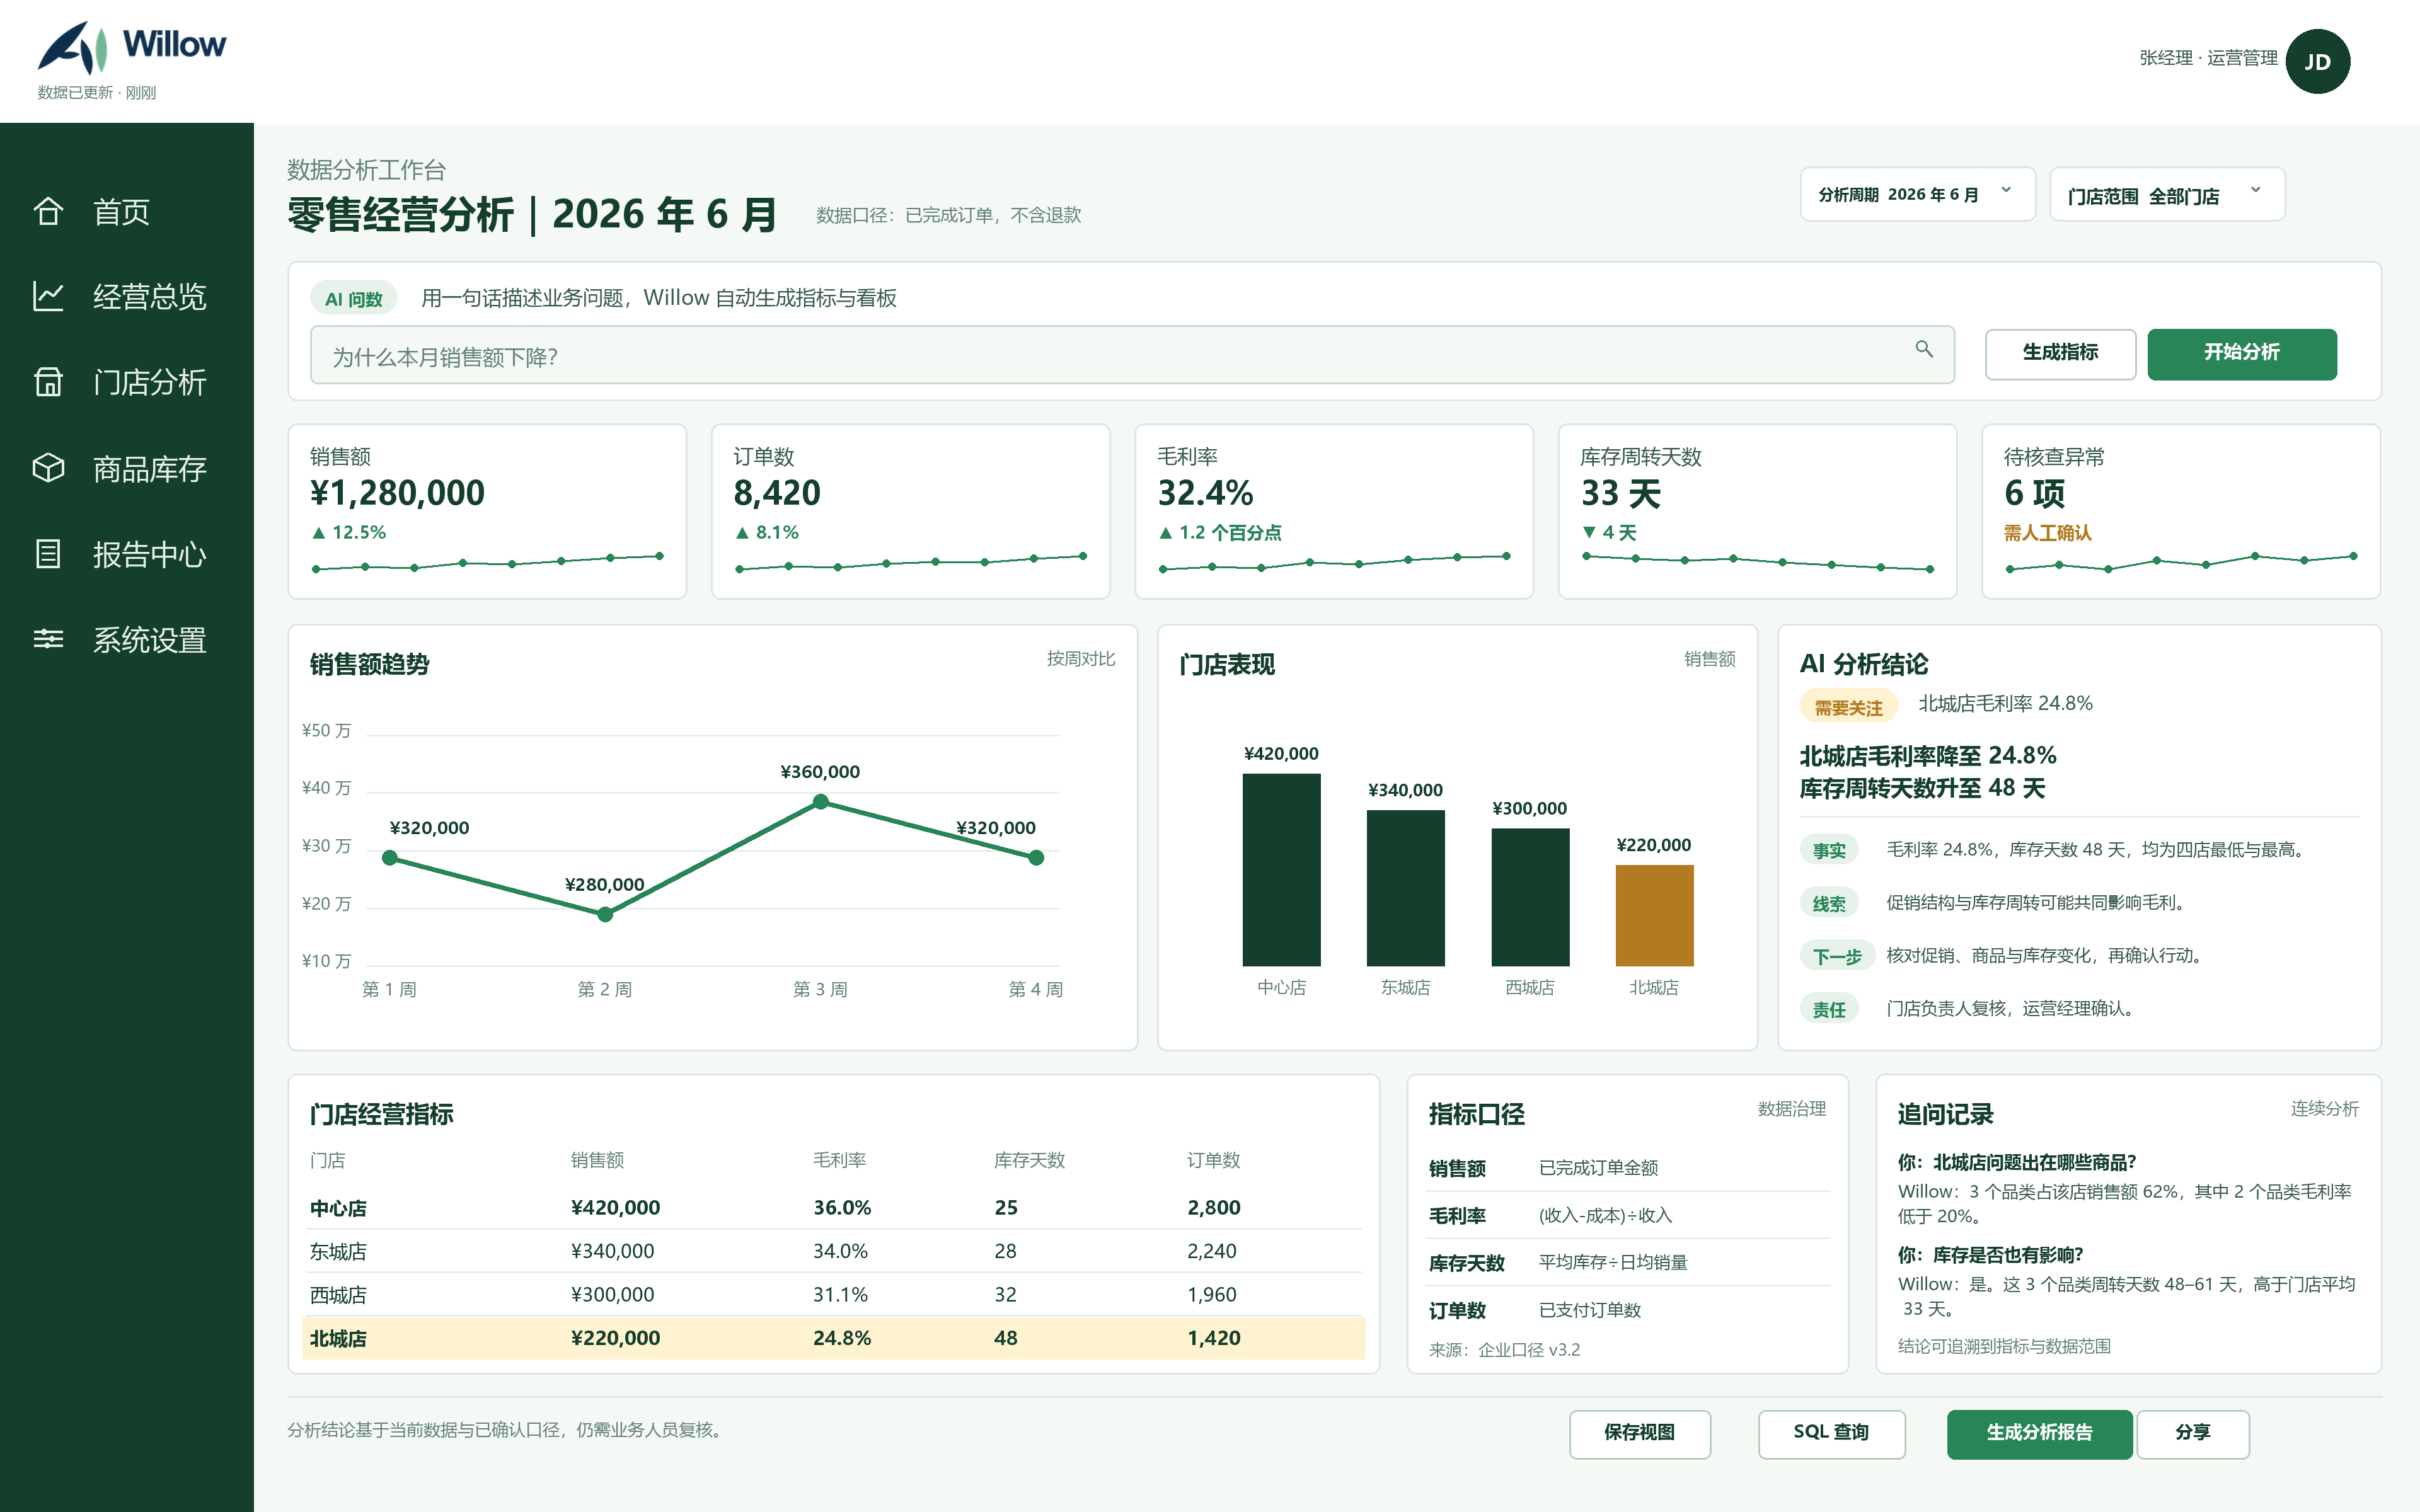
Policy, customer, member, claims, provider and review follow-up information, with sources, scope, data quality and exclusion logic preserved.
JUDGMENT
Risks are not conclusions
Loss ratio pressure, provider anomalies, claim denial reasons and FWA serve only as explainable leads for human review, not as established facts.
ACTION
Bring evidence into the loop
Risk rules, evidence snapshots, AI summaries, human claims review, follow-up tasks and rescan verification are organized into one workflow.
Bring claims performance and risk assessments back to evidence.
Changes in claims performance need reviewable risk signals, source data and human assessment. Organize multi-level performance data, explain risk signals, preserve evidence and support human review and follow-up. Designed with demonstration materials; risk signals are not established facts. Confirm integration and implementation scope.
Conditions for getting started
Designed / Demo materials available · Designed with demonstration materials; risk signals are not established facts. Confirm integration and implementation scope.